What the case is about
The plaintiff is a Theriva stockholder of about four years. The verified complaint brings two claims:
- Federal proxy rules (Section 14(a) and Rule 14a-9). The complaint alleges that Theriva's June 29, 2026 proxy statement told stockholders in one place that Proposal 5, approval to issue up to 16,184,560 warrant shares, was "routine" and that brokers could vote it without instructions, and in another place that it was "non-routine" and that brokers could not. Theriva reported that Proposal 5 passed with 3,665,312 votes for, 2,267,592 against and 10,823,826 broker non-votes.
- Nevada corporate law and Theriva's bylaws. The complaint alleges that the December 2025 proxy stated a 34% quorum although the bylaws set one-third, and that at the December 15, 2025 special meeting in Rockville, Maryland, a continuation date of December 22 was announced, which the company did not hold. Three stockholders who attended have given sworn statements about the meeting. Later sessions were held in Spain.
The plaintiff asks the court to preserve the status quo on the warrants while the court reviews the case, to order Theriva to produce its voting and tabulation records, and to declare the parties' rights. The full requests are in the complaint's Prayer for Relief.
Court filings
Copies provided by the plaintiff. The court's own record on PACER is the official version.
-
PDF · 3.5 MBLatest supplemental filing: Motion for Leave, Supplemental Exhibits SQ, SR and SS, Supplemental Statement in Support of Interim Relief, and the StockTwits and warrant-holder discovery motionsPrepared September 27, 2026; submitted to the Court · 73 pages · Asks leave to add Exhibits SQ–SS and asks the Court to keep the status quo on the new warrant shares, any reverse split and any rights plan while the case is reviewed.
-
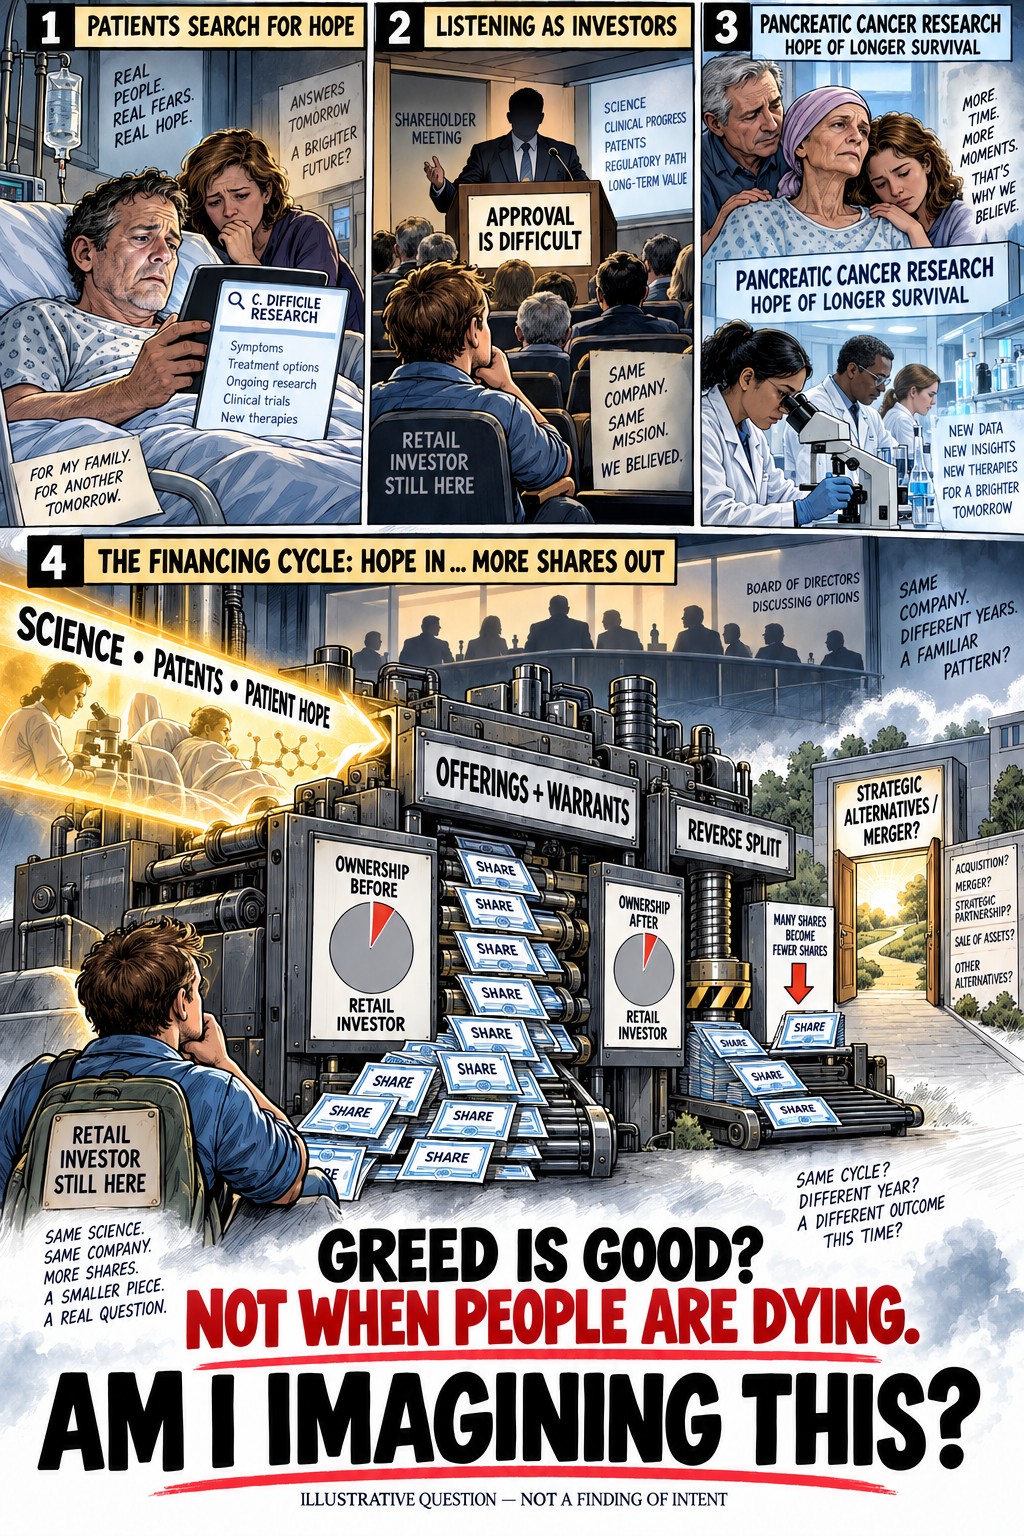
PDF · 19.7 MBSupplemental Exhibits SA–SP, with cover sheets and graphicsSeptember 24, 2026 · 177 pages · Share-count history, reverse splits, warrant and offering timeline, trading volume around company news, R&D spending, and the two graphics shown at the top of this page.
-
PDF · 11.8 MBAddendum packet: Motion for Leave, complete Verified Complaint, Proposed Supplemental Memorandum, and two NoticesSigned September 18–19, 2026; filed and served on Theriva · 115 pages · The complaint as first received was missing pages 4–11; this packet supplies the complete 25-page complaint (Attachment A, pp. 10–38). Attachment B (pp. 39–110) is the Proposed Supplemental Memorandum (the addendum), submitted under LR 7-2(g); the Court has not yet ruled on the motion for leave. Pp. 112–115 are the Notice and Renewed Demand for Jury Trial (ECF No. 7) and the Notice of Administrative Case Classification Discrepancy (ECF No. 6).
-
PDF · 0.5 MBCase-opening papers: Verified Complaint, Emergency Motion for TRO, Plaintiff's Declaration, Proposed Order, Certificate of Interested Parties, Exhibit Index, Civil Cover SheetFiled September 16, 2026 (ECF Nos. 2–4) · 47 pages · Unsigned copy as prepared for filing; the signed, file-stamped versions are on PACER. Complaint pp. 1–25, Motion pp. 26–33, Declaration pp. 34–36, Proposed Order pp. 37–40.
-
PDF · 9.7 MBAppendix, Volume 1: Exhibits A–M156 pages · Theriva's bylaws, proxy statements, Forms 8-K and 10-Q, and the October 2025 warrant agreement, all from SEC EDGAR. The three signed affidavits (Exhibits A–C) were filed on paper and appear here as cover sheets only.
-
PDF · 12.6 MBAppendix, Volume 2: Exhibits N–T151 pages · May 2025 offering documents, investor presentation, quarterly reports and prospectus supplements, from SEC EDGAR. Exhibits N–R (correspondence, phone and brokerage records, transcript) were filed on paper and appear here as cover sheets only.
Discovery requests
The records Plaintiff intends to request from Theriva, and from StockTwits by subpoena, once discovery opens. Working list; it changes as the case proceeds.
-
Discovery requests: Theriva Biologics and StockTwitsRequests to Theriva (the SYN-020 licence, directors’ firms, financing, promotion), a proposed subpoena to StockTwits, and a cross-reference to the requests already made in Supplemental Exhibits SA–SP.
-
StockTwits: motion for limited expedited nonparty discovery, declaration, subpoena schedules and proposed orderDated September 26, 2026. Attachment A: 20 document requests, including “Official” badge accounts and posts linking to this case; Attachment B: 12 Rule 30(b)(6) topics.
Docket
| ECF | Date | Entry |
|---|---|---|
| — | Sep 29, 2026 | Plaintiff's supplemental filings reached the Court: Motion for Leave; Supplemental Exhibits SQ, SR and SS; Supplemental Statement; StockTwits discovery package; warrant-holder discovery package. ECF numbers to be added when docketed. |
| — | Sep 26, 2026 | Plaintiff's Notice of Compliance with Minute Order (ECF No. 8). |
| 8 | Sep 23, 2026 | Minute Order (Judge Traum). The motion warrants expedited consideration. Plaintiff to serve the order and motion by Sept 25 and file a Notice of Compliance; Theriva's response due Sept 29, 2026. |
| 7 | Sep 22, 2026 | Plaintiff's Notice and Renewed Demand for Jury Trial under Rule 38. |
| 6 | Sep 22, 2026 | Plaintiff's Notice of Administrative Case Classification Discrepancy. |
| 5 | Sep 17, 2026 | Summons issued as to Theriva Biologics, Inc. |
| — | Sep 17, 2026 | Case assigned to District Judge Anne R. Traum and Magistrate Judge Craig S. Denney. |
| 4 | Sep 16, 2026 | Verified Complaint, with civil cover sheet and exhibits. |
| 3 | Sep 16, 2026 | Certificate of Interested Parties. |
| 2 | Sep 16, 2026 | Emergency Motion for Temporary Restraining Order and/or Preliminary Injunction. |
The official docket is on PACER / CM-ECF for the District of Nevada. If anything here differs from the court's record, the court's record controls.
Public SEC filings cited
Theriva's own filings on the SEC's EDGAR system, which anyone can read for free:
- June 29, 2026 proxy statement (Proposal 5 voting instructions)
- August 4, 2026 Form 8-K (vote results)
- August 11, 2026 Form 10-Q (warrant status, share count; strategic alternatives "including, but not limited to, an acquisition, merger, reverse merger")
- April 30, 2026 proxy statement (Spain meeting)
- April 9, 2026 Form 8-K
- All Theriva filings on EDGAR
Where the court is
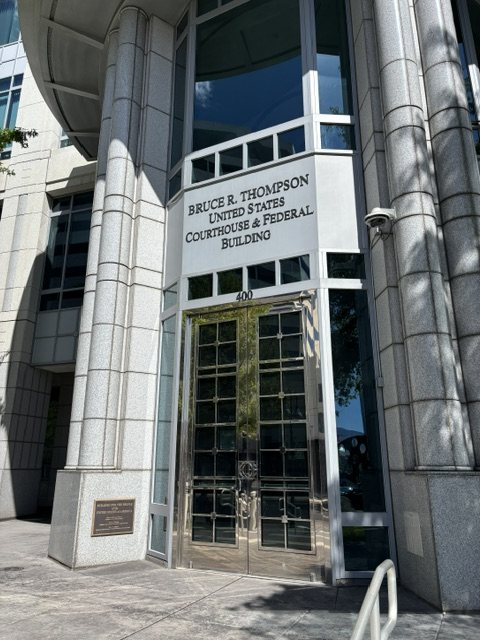
Bruce R. Thompson U.S. Courthouse & Federal Building
400 South Virginia Street, Reno, Nevada 89501